

MD&A · 2025
In this section4 topics
Overview of Operations
Overview of Operations
Supalai Public Company Limited maintains its status as one of Thailand's leading real estate developers with a strong business structure. It diversifies risks through a variety of products, covering both horizontal projects (single-detached houses, semi-detached houses, townhomes) and high-rise projects (condominiums), as well as expanding its revenue base into commercial real estate businesses, including office buildings for rent and hotels. A key highlight of the Group is its strategy of diversifying investments into major provincial cities with high potential, where the Company was one of the first pioneers in the provincial market. As of December 31, 2025, the Group has projects operating in 29 provinces nationwide. This geographical diversification is a key mechanism for increasing market opportunities and reducing risks from over-reliance on any single market. During the period of 2023 - 2025, the overall real estate industry faced several challenging factors, such as economic volatility, stringent credit control measures, earthquake events, persistently high household debt, and sluggish purchasing power. This resulted in a decline in the Group's presales, in line with market conditions. However, in 2025, the Company began to see signs of sales stabilization, with a decrease of only 2 percent compared to the previous year, reflecting its ability to adjust sales strategies effectively to meet the demands of potential markets.
Year 2023 | Year 2024 | Year 2025 | ||||
Million Baht | Increase/(Decrease) Percentage | Million Baht | Increase/(Decrease) Percentage | Million Baht | Increase/(Decrease) Percentage | |
Presales | 28,864 | (11) | 26,743 | (7) | 26,249 | (2) |
Operating Results & Financial Condition
Operating Results & Profitability
Operating Results
1) Revenue from sales of real estate
Year 2023 | Year 2024 | Year 2025 | ||||
Million Baht | Percentage | Million Baht | Percentage | Million Baht | Percentage | |
Revenue from sales of low-rise projects | 20,239 | 66 | 20,610 | 67 | 18,650 | 79 |
Revenue from sales of condominium projects | 10,597 | 34 | 10,207 | 33 | 5,064 | 21 |
Total revenue from sales of real estate | 30,836 | 100 | 30,817 | 100 | 23,714 | 100 |
Revenue from sales of real estate in 2024 was very similar to the previous year, despite it being a challenging year for the real estate market in Thailand. In 2024, the Company had a total of 5 condominium projects completed and due for transfer. Two condominium projects began gradual transfers from the first quarter and continued through the forth quarter, while the other three projects began transfers from the second quarter and also continued through the forth quarter. Nevertheless, revenue from transfers of low-rise projects still showed an increase of approximately 2 percent.
For revenue from sales of real estate in 2025, there was a 23 percent decrease from 2024. The main reason for this decline was a reduction in revenue from condominium project transfers, as the Company had only one condominium project completed and due for transfer this year, with transfers commencing gradually from late the second quarter and continuing through the forth quarter. In contrast, in 2024, the Company had a total of 5 condominium projects completed and due for transfer. For low-rise projects in 2025, revenue decreased by 10 percent, which aligns with the real estate market conditions affected by negative economic factors and purchasing power. Consequently, the majority of this year's primary revenue came from low-rise projects, accounting for 79 percent of total real estate sales revenue.
2) Revenue from rental and services
Year 2023 | Year 2024 | Year 2025 | ||||
Million Baht | Percentage | Million Baht | Percentage | Million Baht | Percentage | |
Revenue from rental real estate | 253 | 74 | 265 | 70 | 289 | 70 |
Revenue from hotel business | 87 | 26 | 113 | 30 | 122 | 30 |
Total revenue from rental and services | 340 | 100 | 378 | 100 | 411 | 100 |
Revenue from rental real estate: The Group's revenue from rental real estate has grown continuously, with Baht 289 million in revenue in 2025. The primary source of revenue is office building rental fees from the Supalai Grand Tower project, which consistently maintains a high average occupancy rate of approximately 90 percent. Furthermore, the increased revenue is supported by the expansion of investments in the Supalai Icon Service Residence Sathorn project, as well as retail rental spaces in the Supalai Icon Sathorn project, which were completed and began recognizing revenue from mid-2024 onwards.
Revenue from hotel business: The hotel businesses managed by the Group, namely 1. Supalai Pasak Resort & Spa, Saraburi Province, and 2. Supalai Scenic Bay Resort & Spa, Phuket Province, showed clearly improved operating results in line with the recovery of the tourism industry. In 2024, revenue expanded by 30 percent compared to 2023, and in 2025, it continued to grow by another 8 percent. The main factors were higher occupancy rates and an increase in the average room rate compared to the previous year.
3) Gross Profit Margin of Real Estate Business
The Group's gross profit margin from its real estate business for 2023 – 2025 was 36 percent, 38 percent, and 34 percent, respectively, consistently maintaining a level higher than the industry average. This reflects efficient cost management and quality construction control. The Company focuses on the following key strategies:
Construction material cost management Develop cooperation with business partners to enhance material quality and manage costs with maximum efficiency.
Construction process development Work closely with contractors to increase efficiency and speed in construction, resulting in timely project delivery and related cost savings.
However, in 2025, the gross profit margin decreased to 34 percent. The main factor was a change in the product mix for transfers, with a significant increase in the proportion of low-rise project transfers to 79 percent, compared to 67 percent in the previous year. This is due to only one new condominium project with a higher gross profit margin being delivered this year. Another factor is increased price competition. Nevertheless, the Company remains committed to maintaining operational standards to ensure the long-term sustainability of profit margins.
4) Selling and Administrative Expenses
Year 2023 | Year 2024 | Year 2025 | ||||
Million Baht | Percentage of total revenue | Million Baht | Percentage of total revenue | Million Baht | Percentage of total revenue | |
Selling expenses | 1,963 | 6.2 | 1,994 | 6.2 | 1,700 | 6.9 |
Administrative expenses | 1,894 | 5.9 | 2,308 | 7.2 | 2,104 | 8.5 |
Total selling and administrative expenses | 3,857 | 12.1 | 4,302 | 13.4 | 3,804 | 15.4 |
Selling expenses: In 2025, the Group's selling expenses amounted to Baht 1,700 million, a decrease of 15 percent compared to 2024, which is consistent with the decline in revenue from real estate transfers. However, when considering the proportion to total revenue, it slightly increased to 6.9 percent (from 6.2 percent in 2024). The main reason for this is the decrease in the total revenue base this year, in line with the revenue recognition cycle from condominium projects. The Group continues to prioritize managing marketing and sales promotion budgets for maximum efficiency amidst challenging market conditions.
Administrative expenses: The Group's administrative expenses in 2025 amounted to Baht 2,104 million, a decrease of 9 percent from the previous year. The proportion to total revenue was 8.5 percent, showing a continuous increase from 5.9 percent in 2023 and 7.2 percent in 2024. This increase in proportion reflects the expansion of operations, as the Group continuously launched new projects to drive future growth, leading to increased project management-related expenses corresponding to the number of projects spread across the country and internationally.
5) Share of profit from investments in joint ventures and associates
The Group's performance from its share of profit from investments in joint ventures and associates has shown remarkable and continuous growth over the past three years. The value increased from Baht 247 million in 2023 to Baht 394 million in 2024, and significantly grew to Baht 730 million in 2025, representing an increase of Baht 336 million or 85.5 percent growth compared to the previous year.
The primary driver of growth in 2025 stemmed from the outstanding performance of joint ventures and associates in Australia, which saw a significant increase in property transfers and revenue recognition from new projects in which the Group made additional investments during 2024. As a result, there are currently a total of 24 projects that have begun gradual transfers and recognized profits returning to the Group. This strategic expansion of the investment portfolio not only helps generate stable profits but also serves as a crucial mechanism for geographical risk diversification and effectively mitigating the impact of a slowdown in the domestic real estate market.
6) Financial Cost
The Group's financial cost for 2023 – 2025 were Baht 467 million, Baht 709 million, and Baht 725 million, respectively. In 2025, financial costs increased by only Baht 16 million from the previous year, or an increase of merely 2.3 percent. The primary reason for the upward trend in financial costs during 2024 – 2025 is the Group's continuous expansion of investments and development of real estate projects, which necessitates securing funding through loans and bond issuance to support growth.
Regarding interest rate management, although the Group was affected by policy interest rate hikes and increased borrowing in 2024, in 2025, the Group was able to stabilize its interest costs. This aligns with the downward trend in policy interest rates and the strategy of securing low-cost funding through appropriate bond issuance. As a result, the Company's average financial cost rate as of December 31, 2025, remained at a low level of only 2.17 percent per annum, which clearly reflects the Group's strong financial position and credibility in the capital market.
7) Income Tax Expense
The Group's income tax expenses for 2023 – 2025 were Baht 1,586 million, Baht 1,665 million, and Baht 1,057 million, respectively. This translates to an effective tax rate, when compared to profit before income tax expense, of 20.7 percent, 21.0 percent, and 20.6 percent, respectively, which is consistent with the corporate income tax rates in Thailand and the countries where the Group has invested.
The components of the Group's income tax expenses are classified into two main parts as follows:
Current income tax The Group records this based on the amount expected to be paid to government tax authorities, calculated from taxable profit according to the criteria specified in the tax laws of each country.
Deferred income tax This involves recording temporary differences between the carrying amounts of assets and liabilities and their related tax bases. The Group recognizes deferred income tax assets when it is probable that future taxable profits will be available to utilize those differences. The Group reviews the carrying amount at the end of each reporting period to reflect the value expected to be actually realized.
Regarding Pillar Two income taxes, the Group falls within the scope of the Pillar Two model rules published by the Organisation for Economic Co-operation and Development (OECD). Therefore, the Group applies the exemption from recognizing and disclosing information regarding deferred income tax assets and liabilities related to these tax rules, even though the Group operates in countries where such laws have been effective since January 1, 2024 (e.g., Australia). However, during 2025, the Group has not recognized any current income tax expenses related to Pillar Two income tax, as it has benefited from the Transitional Safe Harbour measures as prescribed by law.
8) Profit for the year
The Group's profit for the year attributable to equity holders of the Company over the past three years reflects market conditions and the timing of real estate project transfers. In 2023, the Group's profit for the year was Baht 5,989 million, increasing to Baht 6,190 million in 2024, representing a growth of approximately Baht 200 million (a 3 percent increase). This was a result of improved gross profit margins and increased recognition of share of profit from joint ventures.
However, for 2025, the Group's profit for the year attributable to equity holders of the Company amounted to Baht 4,015 million, a decrease of Baht 2,175 million or 35 percent compared to the previous year. The main reasons for this were a decrease in revenue from real estate transfers due to fewer new condominium projects being completed and delivered compared to 2024, coupled with a decline in gross profit margin as the proportion of low-rise project transfers increased this year.
Although the operating results in 2025 were affected by a decrease in the number of newly completed condominium projects compared to the previous year, the Group has maintained a strong future revenue base.
As of December 31, 2025, based on the data of contracts awaiting transfer, the Group has total expected future revenue from contracts amounting to Baht 14,817 million, an increase from Baht 12,304 million in the previous year. This data indicates that the Group has a relatively certain pipeline of recognized revenue and a positive growth trend compared to the previous year, which will be a crucial factor in driving profits and building confidence in operations for 2026 and subsequent years.
9) Net Profit Margin
The Group has consistently maintained a net profit margin at an outstanding level, higher than the industry average. During 2023 – 2025, the Group's net profit margins were 19 percent, 19 percent, and 16 percent, respectively. The decrease in net profit margin in 2025 was primarily due to a reduction in revenue from condominium project transfers in line with the delivery cycle, leading to a decrease in gross profit margin as the proportion of low-rise project transfers increased. Additionally, the proportion of administrative expenses relative to total revenue increased due to continuous expansion of investments in new projects.
For dividend payments The Company remains committed to consistently generating good returns for shareholders, with a dividend payout policy of no less than 35 percent of net profit. Based on the operating results for 2023 – 2025, the Company declared dividends per share of Baht 1.45, Baht 1.45, and Baht 1.25, respectively. This reflects the Group's strong cash flow position and confidence in its long-term growth potential, even amidst challenging economic conditions.
Liquidity & Capital Adequacy
Liabilities
The Group effectively manages its debt structure in line with its business expansion plans. Total liabilities at the end of 2023 were Baht 34,661 million, increasing to Baht 42,011 million in 2024, and reaching Baht 44,499 million in 2025. Key liability items with significant changes are detailed as follows:
1) Bills of exchange payables
The Group secures low-cost short-term working capital through bills of exchange, with their value at period-end increasing from Baht 4,968 million in 2023 to Baht 4,961 million in 2024, and expanding to Baht 6,163 million in 2025, to accommodate the rising demand for working capital.
2) Long-term loans from banks
The outstanding balance at the end of 2023 was Baht 8,523 million, significantly increasing to Baht 11,914 million in 2024 due to expanded investments in new projects both in Thailand and Australia, and then decreasing to Baht 9,961 million in 2025 from loan repayments according to contractual terms. This demonstrates the ability to manage cash flow and reduce interest-bearing debt.
3) Debentures
The Company has continuously increased its proportion of capital raising through the capital market, with debenture values at period-end rising from Baht 13,673 million in 2023 to Baht 17,312 million in 2024, and reaching Baht 21,864 million in 2025. The issuance of debentures for investment expansion allows the Group to manage its average financial costs at a low and stable level for a longer period. In 2024, the Company repaid matured debentures totaling Bah 7,220 million and issued new debentures amounting to approximately Baht 11,000 million. During 2025, the Company repaid matured debentures totaling Baht 9,800 million and issued new debentures amounting to approximately Baht 14,500 million.
Shareholders' equity
The Group's capital base is stable and continuously growing. Total shareholders' equity at the end of 2023 was Baht 51,465 million, increasing to Baht 54,220 million in 2024, and reaching Baht 54,786 million in 2025. This growth reflects the increasing net profit from operations each year, despite dividend payments to shareholders and the implementation of a share repurchase program worth Baht 958 million in 2025 to optimally manage excess liquidity. Details of the Company's share repurchase program for financial management are as follows:
In 2025, the Board of Directors approved a share repurchase program for financial management, totaling 120 million shares (par value of Baht 1 per share), representing 6.14 percent of all issued shares, with a maximum budget not exceeding Baht 2,000 million. The Company will repurchase shares on the Stock Exchange of Thailand from May 19, 2025, to November 18, 2025, and the repurchased shares are scheduled to be resold after 3 months from the completion of the repurchase, but not exceeding 3 years.
Reconciliation of treasury stocks
Number of shares | Average price per share | Repurchase amount | |
(Shares) | (Baht) | (Thousand Baht) | |
Treasury stocks | |||
Repurchase during the year | 66,599,900 | 14.38 | 957,816 |
Treasury stocks as at December 31, 2025 | 66,599,900 | 14.38 | 957,816 |
Liquidity and Cash Flow
Liquidity and Cash Flow: The Group prioritizes managing liquidity and cash flow at appropriate levels sufficient for business operations. The analysis details are as follows:
(Unit: Million Baht) | |||
Year 2023 | Year 2024 | Year 2025 | |
Net cash flows from (used in) operating activities | (180) | (687) | 853 |
Net cash flows from (used in) investing activities | 3,980 | (2,151) | (1,737) |
Net cash flows from (used in) financing activities | (407) | 3,973 | (437) |
Translation adjustments | 3 | (723) | (14) |
Net increase (decrease) in cash and cash equivalents | 3,396 | 412 | (1,335) |
Net cash flows from (used in) operating activities: The trend of cash flow from operations demonstrates success in revenue recognition from property transfers. From a net cash outflow of Baht 180 million in 2023 and Baht 687 million in 2024 (due to significant expansion of investments in projects and land), it has remarkably turned into a net cash inflow of Baht 853 million in 2025. This net cash is derived from core operations through efficient property transfers and project cost management.
Net cash flows from (used in) investing activities: The Group continues to expand its investments to generate future returns. In 2023, there was a net cash inflow from investing activities of Baht 3,980 million due to the disposal of financial assets. In contrast, 2024 and 2025 saw net cash outflows of Baht 2,151 million and Baht 1,737 million, respectively. The main factor was additional investment in property development projects in Australia to diversify risks and establish new revenue streams abroad.
Net cash flows from (used in) financing activities: The Group maintains a flexible capital structure. In 2023, there was a net cash outflow of Baht 407 million from debt repayment and debenture redemption. Subsequently, in 2024, there was a net cash inflow of Baht 3,973 million from capital raising through debentures and bank loans for investment expansion. In 2025, there was a net cash outflow of Baht 437 million, used for long-term loan repayments and dividend payments to shareholders, despite the issuance of new debentures worth Baht 14,500 million to enhance liquidity. Overall, in 2025, the Group had sufficient cash flow to repay debts and provide returns to shareholders exceeding the amount of additional borrowings, reflecting a stable and reliable financial position.
Liquidity Analysis
The Group consistently maintains a safe level of liquidity, as evidenced by:
Liquidity Ratios at the end of 2023 was 2.86 times, adjusted to 2.44 times in 2024, and 2.66 times in 2025.
Quick ratio at the end of 2023 – 2025 were 0.18 times, 0.17 times, and 0.14 times, respectively. Although the quick ratio is low, which is typical for real estate development businesses where most assets are property development costs, the consistently high current ratio of over 2 times reflects strong short-term debt repayment capability.
Capital Adequacy
The Group strictly maintains its financial position in accordance with covenant requirements. The debt-to-equity ratio at the end of 2023 was 0.67 times, adjusted to 0.77 times in 2024, and 0.81 times in 2025, which remains significantly below the control threshold of 2.00 times. Meanwhile, the net gearing ratio was 44 percent in 2023, 54 percent in 2024, and 62 percent in 2025. This increase aligns with the plan to expand investments to generate sustainable revenue and profit growth in the future, and is still considered low compared to companies in the same industry.
Asset Management Capability
Assets
As of the end of 2023 – 2025, the Group's total assets amounted to Baht 86,126 million, Baht 96,231 million, and Baht 99,285 million, respectively. The asset growth in 2024 – 2025 was primarily driven by continuous investment in expanding property development projects, including property development costs to support future deliveries, the expansion of investment portfolios in joint ventures and associates abroad, and the management of investment properties. Key asset items are detailed as follows:
1) Property development costs
As of the end of 2023 – 2025, the values were Baht 71,125 million, Baht 74,641 million, and Baht 77,448 million, respectively. This asset item shows a continuous upward trend in line with the Group's business expansion strategy, representing the cost of work-in-progress for low-rise development projects and condominium projects currently for sale and under development. These will be gradually recognized as revenue from transfers of ownership in line with project delivery schedules from 2026 onwards.
2) Long-term loans to related parties and accrued interest
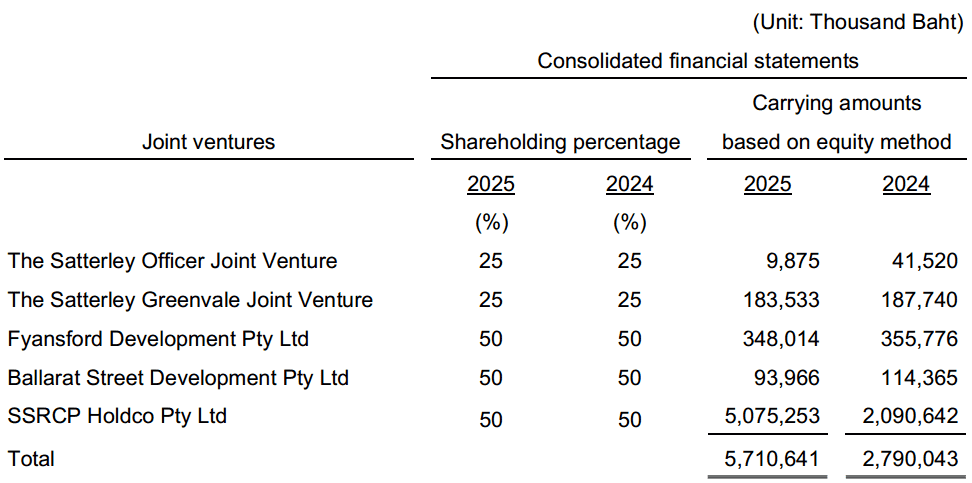
As of the end of 2023 – 2025, the values were Baht 1,220 million, Baht 3,546 million, and Baht 5,053 million, respectively. The significant increase in 2024 and 2025 resulted from expanding the investment base in property development projects in Australia, particularly by increasing the investment proportion through the SSRCP Holdco Pty Ltd joint venture to establish a sustainable long-term profit base.
3) Other financial assets
Other current financial assets: As of the end of 2023 – 2025, the values were Baht 427 million, Baht 230 million, and Baht 214 million, respectively. The majority of these are investments in equity instruments of listed companies.
Other non-current financial assets: As of the end of 2023 – 2025, the values were Baht 4,127 million, Baht 3,295 million, and Baht 1,853 million, respectively. The decrease in value in 2025 was due to the disposal of some equity investments to optimize portfolio management and liquidity.
4) Investments in joint ventures and associates
Joint Ventures: experienced significant growth, especially in 2024, due to additional investment in the SSRCP Holdco Pty Ltd project in Australia. The joint venture, jointly controlled by the Group and other companies, has the following details:
Associates: Investment in associates, which are investments in entities engaged in property development and established in Australia, are detailed as follows:
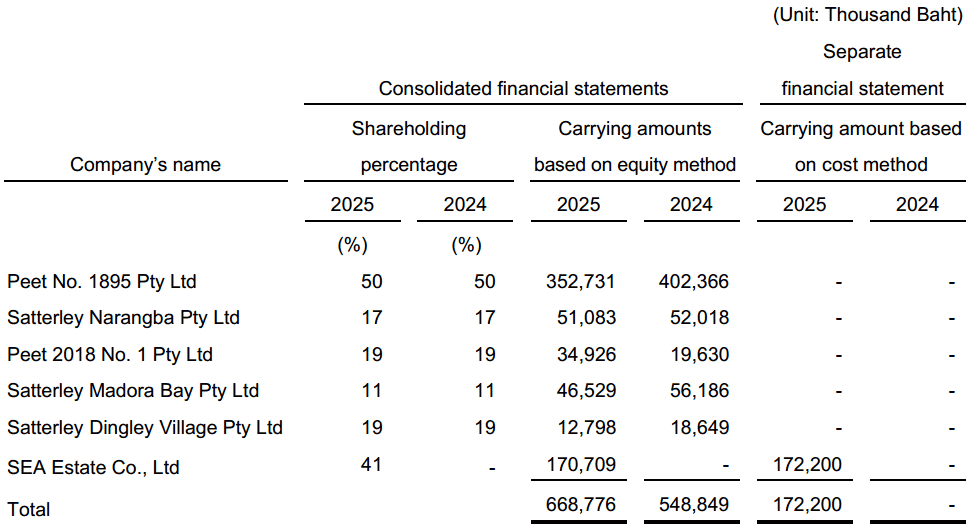
In addition to overseas investments, in 2025, the Company diversified its risks by investing in SEA Estate Co., Ltd. (SEA) with a 41 percent stake to jointly develop buildings and factories for rent in Thailand. The Company has already paid Baht 172 million for its share of the initial capital call.
5) Investment properties
As of the end of 2023 – 2025, the values were Baht 1,072 million, Baht 3,825 million, and Baht 2,624 million, respectively. The majority of these assets comprise office buildings for rent (Supalai Grand Tower), hotel businesses, and retail spaces for rent in the Supalai Icon Sathorn project, as well as a hotel building of a subsidiary that commenced operations in 2007. Additionally, in 2015, Hatyai Nakarin Co., Ltd. opened the ASEAN PLAZA department store in Songkhla province. In 2025, the value of investment properties decreased due to the Group's policy of selling certain office spaces previously held for rent, aiming to rotate assets and recognize operating profits.
6) Asset Management Efficiency Ratios
In 2025, despite challenges in the real estate industry due to slowing purchasing power, the Group maintained efficient asset management standards to ensure an appropriate cash cycle, with details as follows:
Return on Assets: For the return on assets during 2023 – 2025, it was 6.95 percent, 6.43 percent, and 4.04 percent, respectively. The decrease in 2025 reflects the asset accumulation phase to support future growth (Investment Phase), as evidenced by the increase in total assets to Baht 99,285 million, primarily comprising investments in property development costs of Baht 77,448 million and an increase in overseas joint venture investments to Baht 5,711 million. These quality assets will gradually be recognized as revenue and profit from 2026 onwards, based on the backlog of transfers amounting to Baht 14,817 million, which has a high certainty of revenue recognition.
Asset Turnover Ratio: The Group's asset turnover ratio for 2023 – 2025 was 0.38 times, 0.35 times, and 0.25 times, respectively, decreasing in line with the decline in total revenue in 2025 and the expansion of land investments for new project development. Nevertheless, good asset quality management remains a crucial foundation for maintaining the strength of the financial structure and preparing for significant revenue generation from transfers of ownership in the next fiscal year.
Debt Obligations & Off-Balance-Sheet Management
The Group has a cautious policy for managing commitments and contingent liabilities to maintain financial stability and ensure sufficient liquidity to support future obligations. Key points are summarized as follows:
1) Capital commitments The Group has outstanding contractual commitments to support continuous growth and project development, as follows:
Project construction contracts: As of December 31, 2025, the Group had contractual construction commitments totaling Baht 6,101 million, an increase from Baht 5,809 million in 2024, which is consistent with the current expansion plans and increased project development.
Land purchase contracts: The outstanding commitment amounted to Baht 2,262 million in 2025, a slight decrease from Baht 2,475 million in 2024, reflecting the gradual transfer of land for development according to the plan.
Investments in joint ventures and associates: The Group has commitments for uncalled share capital for operations in Australia amounting to AUD 86 million in 2025, a decrease from AUD 158 million in 2024, due to gradual payments according to investment cycles.
2) Guarantee The Group utilizes financial instruments to support the normal operations of its real estate business.
Guarantee utility usage: As of the end of 2025, the amount was Baht 4,724 million, an increase from Baht 4,573 million in 2024. The majority of this obligation is collateral for the provision of public utilities under land allocation laws.
Guarantee trade creditors: Remained stable at Baht 21 million in both 2024 and 2025.
3) Litigation As of December 31, 2025, the Group was sued in various cases related to breach of contract and claims for damages, with a total capital value of approximately Baht 127 million (an increase from Baht 60 million in 2024). Although the cases are still under consideration by the Court of Appeal and the Supreme Court, based on the assessment of the legal and management departments, the Group is confident that it will not suffer significant damages. Therefore, no provision for liabilities has been made for these items in the financial statements.
From the above, it can be seen that the Group systematically manages off-balance sheet commitments. The majority of these commitments are normal items arising from business operations, such as construction and public utility guarantees. The Group has sufficient cash flow and credit lines from financial institutions to support these obligations. Regarding lawsuits, although the capital value of the claims has increased, when compared to the total asset size, which is almost Baht 100,000 million, these obligations are considered low-risk and do not significantly impact the Group's financial stability.
Other Analysis
| Title | Description | |||||||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Analysis of key financial ratios compared to industry averages | Analysis of Key Financial Ratios Compared to Industry Average as of December 31, 2025From the comparative analysis of the Group's financial performance indicators against the average of leading companies in the real estate industry, it is found that the Group possesses competitive capabilities and a financial status that significantly surpasses the industry average in all dimensions, as detailed in the table below.
Note: The industry average is calculated from the financial data of 12 leading listed companies in the real estate development sector, including the Company, namely: 1. AP (Thailand) Public Company Limited 2. Land and Houses Public Company Limited 3. L.P.N. Development Public Company Limited 4. Pruksa Real Estate Public Company Limited 5. Quality Houses Public Company Limited 6. SC Asset Corporation Public Company Limited 7. Sansiri Public Company Limited 8. Ananda Development Public Company Limited 9. Origin Property Public Company Limited 10. AssetWise Public Company Limited 11. Sena Development Public Company Limited and 12. Supalai Public Company Limited. The data from the financial ratio comparison above reflects that the Group continues to maintain operational standards efficiently, surpassing the industry average in all aspects. Key points can be summarized as follows: Profitability Performance: The Group's gross profit margin is 34 percent and net profit margin is 16 percent, both significantly higher than the industry average. This demonstrates expertise in managing material costs and effectively controlling construction quality. Cost Control Capability : The ratio of selling and administrative expenses to total revenue is 15 percent, which is lower than the industry average of 21 percent. This reflects agile and highly effective management of marketing budgets and internal operations. Strong Financial Structure: The interest-bearing debt to equity ratio stands at 62 percent, significantly lower than the industry average of 99 percent. This confirms stringent financial discipline and a low level of financial risk, even with continuous investment expansion. Return Generation: The Return on Assets (ROA) at 4 percent and Return on Equity (ROE) at 7 percent remain above the industry average, indicating excellent management capability in utilizing assets and equity to generate returns for shareholders. In summary The results of this comparison confirm the success of a balanced management strategy in terms of growth, profitability, and risk management, which are key factors in building long-term confidence. |
Debt Securities with Financial Ratio Requirements
Debt Securities with Financial Ratio Requirements Issued?
Yes
Can the Company Maintain the Reported Financial Ratios?
Yes
Explanation
Capital Management
The primary objective of the Group's capital management is to maintain an optimal capital structure to support the Group's business operations and enhance shareholder value, as well as to comply with financial covenants stipulated in loan agreements. The Group has complied with these financial covenants throughout the reporting period.
As of December 31, 2025 and 2024, the Group's debt-to-equity ratio is summarized as follows:
|
Consolidated Financial Statements |
Separate Financial Statements |
|||
|
2025 |
2024 |
2025 |
2024 |
|
|
Debt-to-Equity Ratio |
0.81:1 |
0.77:1 |
0.86:1 |
0.81:1 |
Factors That May Affect Financial Condition
Factors or Incidents That May Materially Affect Financial Condition
The outlook for the real estate sector in 2026 remains a period of strategic navigation amidst ongoing challenges and adaptation. Although certain pressures from 2025 have begun to ease, the Company continues to closely monitor key factors that may influence our performance, as follows:
1. Household Debt and Mortgage Loan: While household debt levels have stabilized, financial institutions maintain a stringent and cautious approach to mortgage approvals, particularly in the lower-price segments. To mitigate this, the Company has developed the "Digital Easy Application Loan" (D.E.A.L.), a comprehensive digital lending platform designed to streamline and enhance the efficiency of the credit approval process for our customers.
2. Interest Rate Trends and Financing Costs: Following the policy interest rate reductions from late 2024 through 2025, the shift toward a more balanced interest rate environment has positively influenced consumer purchasing decisions and lowered the Company’s cost of funds for new developments. Nevertheless, we maintain a prudent debt management strategy to safeguard against global financial market volatility and economic shifts.
3. Domestic and Global Economic Volatility: Our international expansion into Australia has become a cornerstone of our Risk Diversification Strategy. In 2025, our Australian portfolio achieved significant growth through new joint venture projects, providing a crucial revenue balance amidst the gradual recovery of the domestic economy.
The Group remains confident that our robust financial position, characterized by a Low Net Gearing Ratio, a diverse product portfolio covering 29 provinces across Thailand, and our steady expansion in Australia, serves as a formidable shield against economic fluctuations. Moreover, our transformation into a Smart Organization—driven by Data Analytics and Artificial Intelligence (AI) to optimize product design and services—coupled with our commitment to ESG principles, will be instrumental in driving continuous growth, enhancing adaptability, and delivering sustainable value to our shareholders, even in a challenging business environment.